When a monsoon storm rolls through Pinal County and damages irrigation equipment, or a livestock trailer is involved in an accident on I-10, Arizona farmers and ranchers face financial risks that standard business insurance simply doesn't cover. That's where agribusiness insurance comes in.
Agribusiness insurance in Arizona is specialized commercial coverage designed to protect farms, ranches, and agricultural operations from the unique risks they face—including crop loss, livestock death, equipment breakdown, and liability claims from farm visitors or employees. Unlike standard commercial policies, agribusiness coverage accounts for seasonal income fluctuations, weather-related perils, and the specific equipment and structures found on agricultural properties across Casa Grande, Maricopa, and the greater Pinal County region.
At Gebhardt Insurance Group, we've been helping Arizona agricultural operations find the right coverage since 2004. This guide explains what agribusiness insurance covers, why it matters for Arizona operations, and how an independent agent can help you protect everything you've built.
What Arizona Farmers and Ranchers Need to Know About Agribusiness Insurance
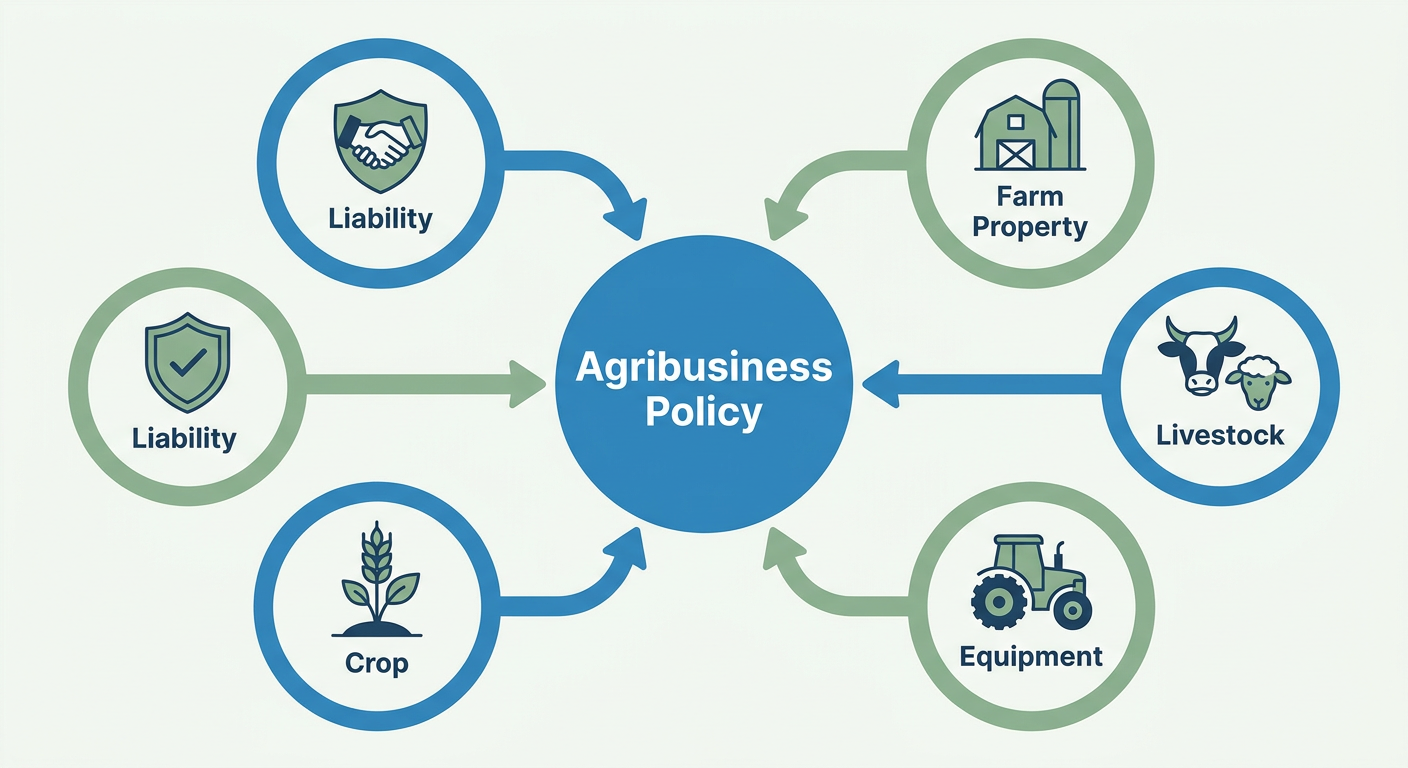
Agribusiness insurance isn't a single policy—it's a combination of coverages tailored to agricultural operations. Understanding what's available helps you identify gaps in your current protection.
Farm property coverage protects buildings, barns, silos, greenhouses, and other structures on your agricultural property. This includes damage from fire, wind, hail, and other covered perils. In Arizona, this coverage often needs to account for monsoon damage, which can be severe in Pinal County between June and September.
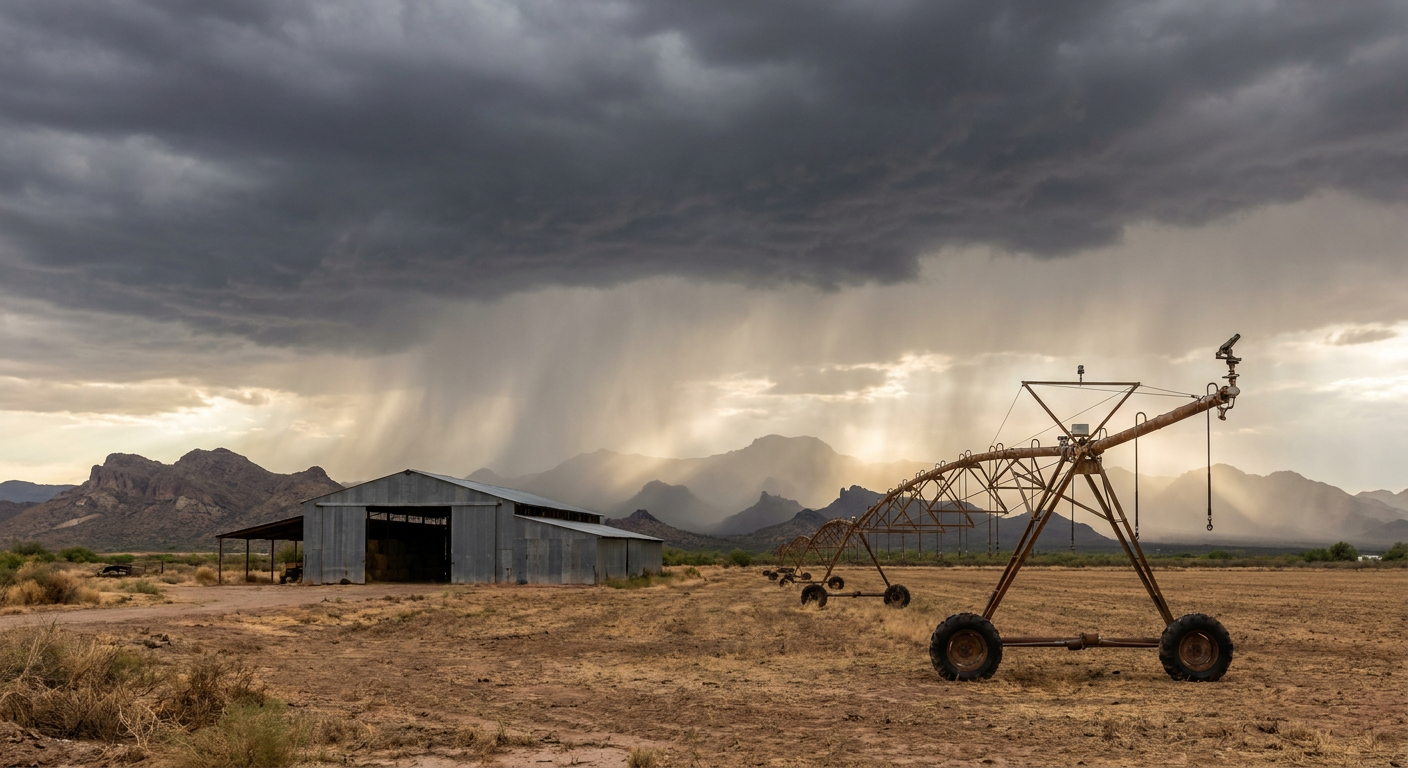
Arizona's intense monsoon season presents unique risks for farm structures and irrigation systems.
Farm equipment and machinery coverage protects tractors, harvesters, irrigation systems, and other equipment essential to your operation. Equipment breakdown coverage—sometimes called mechanical breakdown insurance—covers repair or replacement costs when machinery fails due to mechanical or electrical issues, not just accidents.
Livestock coverage protects cattle, horses, sheep, and other animals from death due to accidents, disease, or extreme weather. Arizona ranchers face specific risks from extreme heat, which can cause livestock losses during summer months when temperatures exceed 110°F.
Crop insurance protects against yield losses from weather, pests, disease, and price fluctuations. While the federal crop insurance program (administered through USDA Risk Management Agency) covers many Arizona crops—including cotton, wheat, and alfalfa—private crop coverage can fill gaps or provide higher protection levels.
Farm liability coverage protects against lawsuits if someone is injured on your property or harmed by your agricultural products. This is essential for operations with farm stands, U-pick activities, agritourism events, or custom harvesting services. Arizona law doesn't require farm liability insurance, but operating without it puts your personal assets at risk.
A common mistake Arizona agricultural operations make is assuming their homeowners insurance covers farm activities—it typically doesn't. If you're running any commercial agricultural operation, even a small one, you need dedicated agribusiness coverage.
How Gebhardt Insurance Group Helps Arizona Agricultural Operations
Finding the right agribusiness insurance isn't as simple as calling one company. Agricultural operations vary dramatically—a 5,000-acre cotton farm in Pinal County has different needs than a 50-head cattle ranch near Florence or a specialty produce operation in Maricopa.
As an independent insurance agency, Gebhardt Insurance Group shops more than 40 A-rated carriers to find coverage that fits your specific operation. We don't sell our own insurance products, which means we're not incentivized to push one company's policies over another. Our team compares options so you don't have to call around.
Steve, Crystal, Maria, Sarah, and Andrea work directly with Arizona agricultural clients to understand their operations—what crops they grow, what livestock they raise, what equipment they own, and what activities happen on their property. This matters because agribusiness policies can be customized in ways that standard commercial policies cannot.
When a claim happens—and in agriculture, claims happen—we advocate on your behalf. Because we work with multiple carriers, we have leverage to push for fair claim settlements. If your current carrier raises rates or reduces coverage at renewal, we can move your policy to a better option without you starting from scratch.
We also conduct annual policy reviews to make sure your coverage keeps pace with your operation. Added a new barn? Purchased additional equipment? Started offering farm tours? These changes affect your insurance needs, and catching gaps before a loss occurs is always better than discovering them after.
Ready to see what agribusiness coverage should cost for your operation? Get a free, no-obligation quote from Gebhardt Insurance Group. Call our Casa Grande office at (520) 836-3244, our Maricopa office at (520) 518-8008, or get a quote online.
Key Factors That Affect Arizona Agribusiness Insurance Costs
Insurance premiums for agricultural operations vary significantly based on several factors. Understanding what drives costs helps you make informed decisions about coverage levels and deductibles.
Type and size of operation: A diversified farm with crops, livestock, and agritourism activities costs more to insure than a single-purpose operation. Larger acreage and higher property values also increase premiums.
Location within Arizona: Operations in flood-prone areas or regions with higher wildfire risk may face higher premiums. Pinal County's location in the monsoon belt affects property coverage rates.
Equipment age and value: Newer equipment costs more to insure but may be more reliable. Older equipment may require equipment breakdown coverage to protect against mechanical failures.
Claims history: Operations with previous claims typically pay higher premiums. Maintaining safety protocols and loss prevention measures can help keep rates lower over time.
Coverage limits and deductibles: Higher coverage limits cost more, but choosing a deductible that's too high can leave you financially exposed after a loss. We help clients find the right balance for their operation.
Bundling coverages: Combining multiple coverages—property, equipment, livestock, liability—with one carrier often results in lower overall premiums than purchasing separate policies.
Arizona agricultural operations can also explore discounts for things like fire suppression systems, security measures, and participation in farm safety programs. Your business insurance agent should actively look for these savings opportunities.
What Coverage Level Does My Arizona Farm or Ranch Need?
Arizona doesn't mandate specific agribusiness insurance coverage levels, so the decision comes down to protecting your investment and managing risk. Most agricultural lenders require certain coverages as a condition of financing, which often sets a minimum baseline.
At minimum, most Arizona agricultural operations should carry farm property coverage for buildings and structures, equipment coverage for machinery and vehicles, general liability coverage with limits of at least $1 million per occurrence, and workers' compensation if you have employees (Arizona law requires workers' comp for most agricultural employees). Operations with livestock should add mortality coverage, and those with significant crop production should explore crop insurance options.
We recommend reviewing your coverage whenever you make significant changes to your operation—purchasing land, adding equipment, starting new agricultural activities, or hiring additional workers.
An independent agent compares dozens of carriers to find the best fit for your specific operation.
How Do I File an Agribusiness Insurance Claim in Arizona?
If you experience a loss on your agricultural operation, document everything immediately—take photos, preserve damaged equipment or structures, and keep records of any emergency expenses. Contact your insurance agent as soon as possible to report the claim.
When you work with an independent agent like Gebhardt Insurance Group, we help guide you through the claims process and communicate with the carrier on your behalf. We can help you file a claim and advocate for fair settlement when disputes arise.
For livestock losses, you'll typically need a veterinarian's statement documenting the cause of death. For crop losses, you may need documentation from an adjuster certified through the USDA Risk Management Agency. For property and equipment losses, the carrier will send an adjuster to assess damage.
Why Should Arizona Farmers Use an Independent Insurance Agent?
Agricultural insurance is complex, and a one-size-fits-all approach rarely works. Independent agents work for you—not for any single insurance company—which means we can objectively compare coverage options across multiple carriers.
This matters because agricultural insurance markets change frequently. A carrier that offered competitive farm coverage last year might raise rates or exit the market entirely this year. When that happens, an independent agent can quickly find alternatives without you starting over.
We also understand Arizona-specific agricultural risks—monsoon flooding, extreme heat, dust storms, irrigation system failures—because we live here. Our Casa Grande and Maricopa offices serve agricultural operations throughout Pinal County, from small hobby farms to large commercial operations.
Most of our new clients come from referrals, which tells us we're doing something right. Check out what our clients say about working with our team.
Common Questions About Arizona Agribusiness Insurance
Does regular business insurance cover farm operations in Arizona?
No, standard commercial policies typically exclude agricultural activities. Farms, ranches, and agricultural operations need dedicated agribusiness coverage designed for their unique risks—including livestock, crops, farm equipment, and seasonal income fluctuations.
What types of livestock does Arizona farm insurance cover?
Livestock coverage in Arizona can protect cattle, horses, sheep, goats, poultry, and specialty animals. Coverage typically includes death from accidents, disease, and extreme weather. Some policies also cover theft and straying.
Is crop insurance required for Arizona farms?
Arizona doesn't require crop insurance, but it's essential protection for operations dependent on crop revenue. Federal crop insurance through USDA covers many Arizona crops, and private policies can supplement federal coverage.
Protect Your Arizona Agricultural Investment
Your farm or ranch represents years of hard work and significant financial investment. The right agribusiness insurance protects that investment from the risks you can't control—weather, accidents, market fluctuations, and liability claims.
Let Gebhardt Insurance Group do the shopping for you. We'll compare coverage options from multiple carriers to find protection that fits your operation and your budget. Call our Casa Grande office at (520) 836-3244, our Maricopa office at (520) 518-8008, or request a free quote online.
This article is for informational purposes only and does not constitute insurance advice or a binding quote. Coverage options, premiums, and policy terms vary by carrier, individual circumstances, and Arizona state regulations. Consult a licensed insurance professional for personalized recommendations. For current rates and coverage options, contact Gebhardt Insurance Group at (520) 836-3244 (Casa Grande) or (520) 518-8008 (Maricopa), or visit gebhardtinsurancegroup.com for a free quote.