Every Arizona driver who registers a vehicle must carry liability insurance—it's state law, and driving without it can mean fines, license suspension, and serious financial risk if you cause an accident. Arizona requires minimum liability coverage of $25,000 per person and $50,000 per accident for bodily injury, plus $15,000 for property damage (25/50/15). These minimums satisfy the legal requirement, but they may leave gaps in your protection depending on your vehicle, assets, and driving habits. This guide breaks down exactly what Arizona law requires, what optional coverages you should consider, and how Gebhardt Insurance Group helps Casa Grande and Maricopa drivers find the right coverage at the right price.
What Arizona Law Requires for Auto Insurance
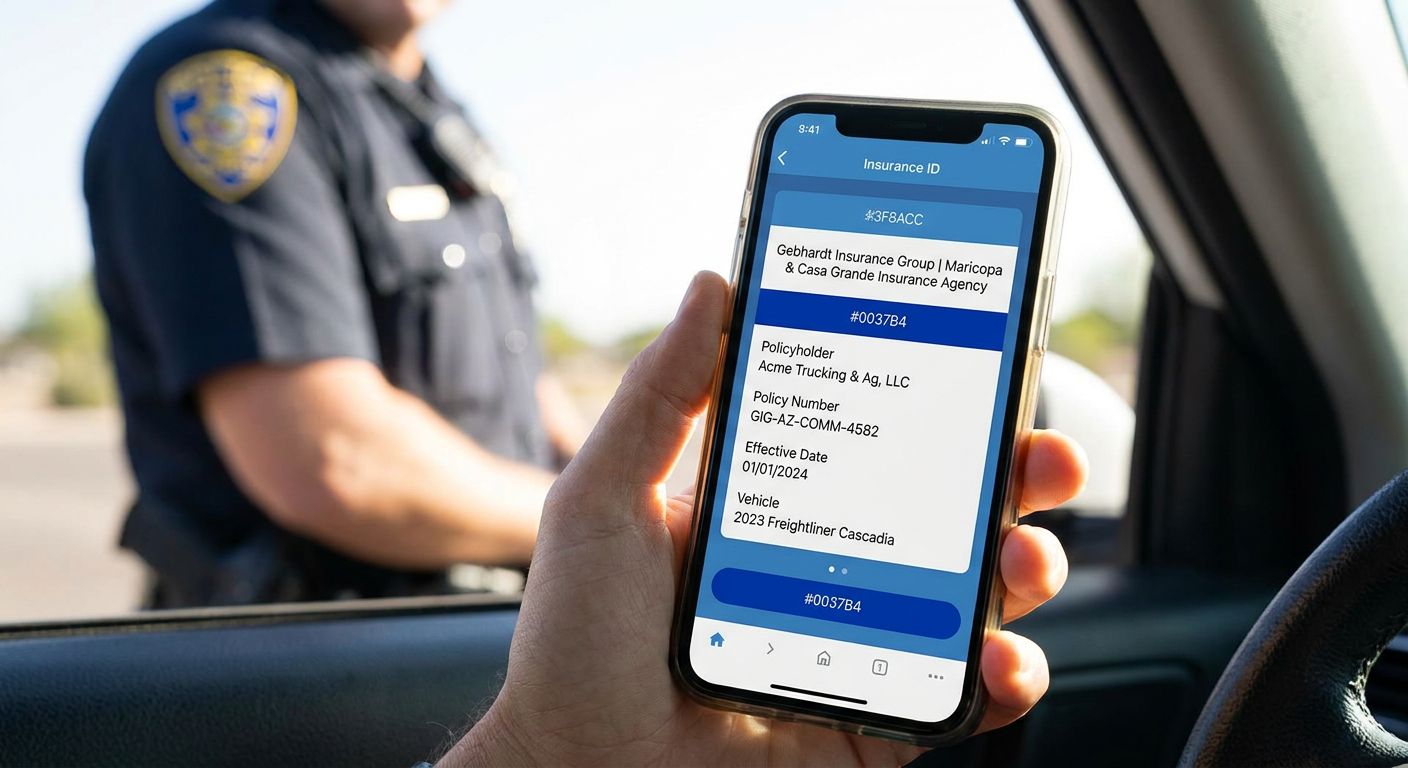
Arizona's mandatory auto insurance law, established under Arizona Revised Statutes § 28-4135, requires all vehicle owners to maintain continuous liability coverage. If you're stopped by law enforcement, involved in an accident, or renewing your registration, you must show proof of insurance.
The state-mandated minimums break down like this:
Coverage Type Arizona Minimum What It Covers Bodily Injury (per person) $25,000 Medical bills, lost wages, pain and suffering for one injured person Bodily Injury (per accident) $50,000 Total medical costs for all injured people in one accident Property Damage $15,000 Repairs or replacement of the other driver's vehicle and property
Liability coverage pays for damages you cause to other people and their property—it does not cover your own injuries or vehicle repairs. That's an important distinction many Arizona drivers miss.
Arizona uses a fault-based insurance system, meaning the driver who causes an accident is financially responsible for damages. If your liability limits are too low and the other party's expenses exceed your coverage, you're personally liable for the difference. With the average new vehicle costing over $48,000 and medical costs climbing every year, the state minimums may not stretch far in a serious collision.
Proof of Insurance Requirements
Arizona accepts several forms of proof, including your insurance card (physical or digital), a policy declaration page, or a letter from your insurer. The Arizona Department of Transportation (ADOT) can electronically verify your coverage status when you register or renew your vehicle.
Driving without insurance in Arizona triggers penalties including a $500 fine for a first offense, potential license and registration suspension, and a requirement to file an SR-22 certificate to reinstate your driving privileges. If you've had a lapse in coverage and need to file an SR-22, our team can help—learn more about SR-22 insurance in Maricopa.
How Gebhardt Insurance Group Helps Arizona Drivers
Understanding requirements is one thing—finding the right policy at a price that fits your budget is another. That's where working with an independent agent makes a real difference.
Gebhardt Insurance Group has served Casa Grande, Maricopa, and the greater Pinal County area since 2004. As an independent agency, we don't sell our own insurance products or represent a single carrier. Instead, we shop more than 40 A-rated insurance companies—including Progressive, AAA, and many others—to compare quotes side by side and find the coverage that fits your situation.
What does that mean for you? One phone call to our office gets you multiple options instead of a single take-it-or-leave-it quote. If your current carrier raises rates at renewal, Crystal or Maria can check whether a different company offers better pricing without you starting over from scratch.
Our team drives the same I-10 corridor, deals with the same monsoon-season road hazards, and understands how Arizona's heat affects vehicles and premiums. When you file a claim, we advocate on your behalf because we have relationships with multiple carriers—not just one. That leverage matters when you need your claim handled fairly and quickly.
Gebhardt earned the AAA Insurance Emerald Achievement Award as a top new policy agency in Arizona, and the Casa Grande Dispatch recognized us for Best Customer Service. Most of our new clients come from referrals, which tells us we're doing something right for our neighbors.
Want to see how much you could save? Get a free, no-obligation quote from Gebhardt Insurance Group. Call our Casa Grande office at (520) 836-3244, our Maricopa office at (520) 518-8008, or get a quote online.
Beyond the Minimums: Coverage Options to Consider
Arizona's 25/50/15 minimums satisfy the law, but they leave gaps that could cost you thousands out of pocket. Here's what else to consider when building your policy:
Higher Liability Limits
If you cause an accident with serious injuries, medical bills can quickly exceed $25,000 per person. Many financial advisors and insurance professionals recommend at least 100/300/100 coverage ($100,000 per person, $300,000 per accident for bodily injury, $100,000 for property damage) if you have assets to protect. The premium difference between minimum and higher limits is often smaller than people expect.
Collision Coverage
Collision coverage pays to repair or replace your vehicle after an accident, regardless of fault. It's typically required if you're financing or leasing, but it's also worth considering if your vehicle's value exceeds what you could comfortably replace out of pocket.
Comprehensive Coverage
Comprehensive coverage handles non-collision damage: theft, vandalism, hail, monsoon flooding, a deer strike on Highway 87, or a broken windshield from a rock kicked up on I-10. Arizona's desert storms and extreme temperatures make comprehensive coverage particularly relevant for Pinal County drivers.
Arizona’s unique weather and road hazards make comprehensive coverage a vital consideration.
Uninsured/Underinsured Motorist Coverage (UM/UIM)
The Insurance Information Institute estimates that roughly 12% of Arizona drivers are uninsured. UM/UIM coverage protects you if you're hit by a driver with no insurance or insufficient limits to cover your injuries and damages. It's one of the most valuable add-ons you can carry.
Medical Payments (MedPay)
MedPay covers medical expenses for you and your passengers after an accident, regardless of who's at fault. It kicks in immediately and can cover deductibles, co-pays, and expenses your health insurance doesn't.
Not sure which coverages make sense for your situation? That's exactly why we offer annual policy reviews—our agents check your current coverage against your life circumstances and make sure you're not overpaying for coverage you don't need or underinsured where it matters. Learn more about how car insurance works to make informed decisions.
What Affects Your Auto Insurance Premium in Arizona
Insurance companies use dozens of factors to calculate your rate. Understanding what moves the needle helps you make smarter decisions—and ask better questions when shopping for coverage.
Driving record: Accidents, tickets, and DUIs stay on your record for 3-5 years and significantly increase premiums. A clean record is your best discount.
Location: Where you live and park your car matters. Urban areas with higher accident rates and theft typically cost more than rural communities. Casa Grande and Maricopa rates differ from Phoenix metro.
Vehicle type: Newer, more expensive vehicles cost more to insure. Sports cars and high-theft models carry higher premiums than practical sedans.
Credit-based insurance score: Arizona allows insurers to use credit history as a rating factor. Maintaining good credit can lower your rate.
Age and experience: Young drivers under 25 pay more due to statistical risk. Rates typically drop as you gain experience.
Coverage levels and deductibles: Choosing higher deductibles lowers your premium—but means more out-of-pocket expense when you file a claim.
Bundling: Combining auto with home insurance or renter's insurance often triggers multi-policy discounts.
Our team can walk you through which factors you can control and which discounts you might be missing. Check out our guide on car insurance discounts for specific ways to lower your premium.
Arizona Auto Insurance Questions Answered
How much does car insurance cost in Casa Grande?
Auto insurance premiums in Casa Grande vary based on your driving record, vehicle, coverage levels, and personal factors—but Pinal County rates are typically lower than Phoenix metro averages. The best way to get an accurate number is to request a personalized quote that accounts for your specific situation.
Can I drive in Arizona with out-of-state insurance?
Yes, if you're visiting Arizona, your valid out-of-state insurance policy covers you. However, if you become an Arizona resident (living here more than 7 months or establishing domicile), you must register your vehicle in Arizona and obtain an Arizona-compliant policy within 15 days. Our guide on how to switch car insurance explains the process.
What happens if I get caught driving without insurance in Arizona?
First-offense penalties include a $500 fine, possible license suspension, and a requirement to carry an SR-22 certificate (proof of financial responsibility) for three years. Repeat offenses escalate to higher fines and longer suspensions. The cost of maintaining minimum coverage is almost always less than the penalties for going without.
Conclusion
Arizona's auto insurance requirements set a legal floor, but the right coverage depends on your vehicle, assets, and risk tolerance. Understanding the difference between minimum compliance and smart protection helps you make decisions you won't regret after an accident.
Let Gebhardt Insurance Group do the shopping for you. Our independent agents compare 40+ carriers to find coverage that fits your needs and budget—no pressure, no obligation. Call our Casa Grande office at (520) 836-3244, our Maricopa office at (520) 518-8008, or get a free quote online.
Frequently Asked Questions
What is the minimum car insurance required in Arizona?
Arizona requires liability coverage of at least $25,000 per person and $50,000 per accident for bodily injury, plus $15,000 for property damage. This 25/50/15 coverage is the legal minimum, though many drivers carry higher limits to protect their assets.
Does Arizona require full coverage auto insurance?
No, Arizona only mandates liability coverage. Full coverage—which typically includes collision and comprehensive—is optional unless your lender or lease agreement requires it. However, liability alone doesn't cover your own vehicle's damage.
How many insurance companies does Gebhardt compare?
Gebhardt Insurance Group shops more than 40 A-rated insurance carriers to find clients the best combination of coverage and price. As an independent agency, we're not limited to one company's products.
Why is my Arizona car insurance so expensive?
Common factors include your driving record, age, credit-based insurance score, vehicle type, and where you live. Arizona's I-10 corridor sees heavy traffic and accident frequency. An independent agent can identify discounts you might be missing and compare rates across carriers.
Do I need uninsured motorist coverage in Arizona?
Uninsured motorist coverage isn't required by Arizona law, but it's highly recommended. With an estimated 12% of Arizona drivers uninsured, UM coverage protects you if you're hit by someone without adequate insurance to cover your injuries and damages.
This article is for informational purposes only and does not constitute insurance advice or a binding quote. Coverage options, premiums, and policy terms vary by carrier, individual circumstances, and Arizona state regulations. Consult a licensed insurance professional for personalized recommendations. For current rates and coverage options, contact Gebhardt Insurance Group at (520) 836-3244 (Casa Grande) or (520) 518-8008 (Maricopa), or visit gebhardtinsurancegroup.com for a free quote.