If you've noticed your car insurance bill creeping higher, you're not alone. Arizona drivers paid an average of $1,821 annually for full coverage in 2024, according to the Bankrate Arizona insurance analysis—and rates in Pinal County can vary significantly based on your ZIP code, driving record, and the coverage you choose.
The most effective way to save on Arizona car insurance is to compare quotes from multiple carriers, bundle your auto and home policies, maintain a clean driving record, adjust your deductibles strategically, and ask about all available discounts. An independent agent can do this comparison shopping for you in a single call, often uncovering savings you'd miss going carrier by carrier.
At Gebhardt Insurance Group, we've helped Casa Grande and Maricopa families find better rates since 2004 by shopping more than 40 A-rated carriers. This guide breaks down the five strategies that actually work for Arizona drivers—no gimmicks, no high-pressure sales, just practical ways to keep more money in your pocket.
What You Need to Know About Arizona Car Insurance Costs
Before diving into savings strategies, it helps to understand what you're required to carry and what drives premiums in this state.
Arizona law requires minimum liability coverage of $25,000 per person and $50,000 per accident for bodily injury, plus $15,000 for property damage. These minimums haven't changed since July 2020, but they represent the legal floor—not necessarily adequate protection if you cause a serious accident on I-10 or hit a late-model truck in the Fry's parking lot.
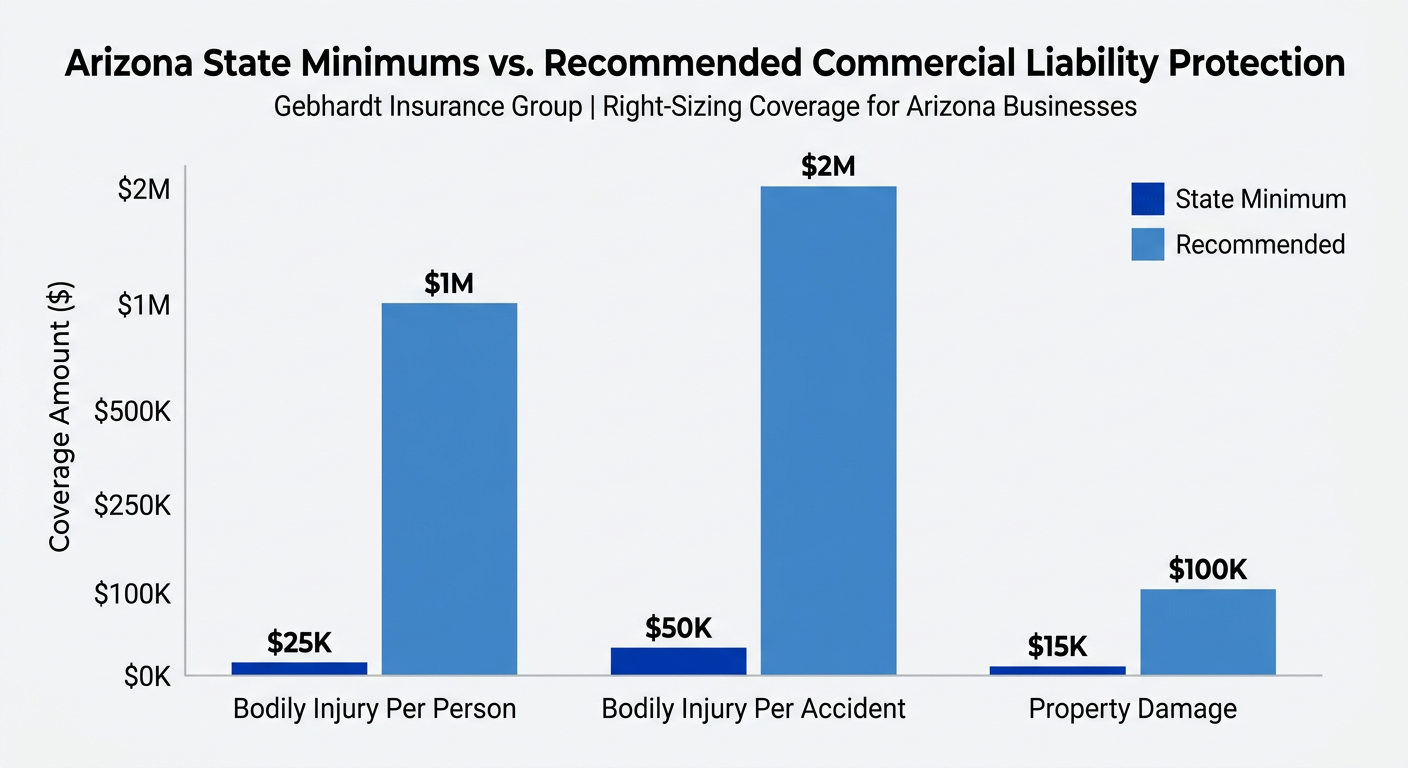
Arizona state minimums often fall short of covering the actual costs of a serious accident.
Several Arizona-specific factors push premiums higher:
Monsoon season damage — Flash flooding, dust storms, and hail between June and September lead to thousands of comprehensive claims each year
I-10 corridor traffic — Casa Grande sits between Phoenix and Tucson on one of the state's busiest highways, increasing accident frequency
Desert heat — Extreme temperatures cause tire blowouts and battery failures, leading to roadside incidents
Rapid population growth — More drivers in Maricopa and Casa Grande means more accidents and higher risk pools
The good news? These same factors create opportunities to save if you know where to look. Understanding how car insurance actually works puts you in a stronger position to make smart coverage decisions.
How Gebhardt Insurance Group Helps Arizona Drivers Save
Here's the reality: calling five different insurance companies, answering the same questions five times, and trying to compare quotes with different coverage structures is exhausting. Most people give up after two or three calls and settle for whatever seems reasonable.
That's exactly the problem an independent agency solves.
When you contact Gebhardt Insurance Group, our team—Steve, Crystal, Maria, Sarah, and Andrea—does the shopping for you. We work with more than 40 A-rated carriers including Progressive, AAA, and dozens of others. One conversation with us generates multiple competitive quotes, all structured with the same coverage levels so you're comparing apples to apples.
Unlike captive agents who can only sell their company's products, we have no incentive to push any particular carrier. If Progressive offers the best rate for your situation this year but AAA beats them next year, we move your policy. No starting over, no new applications.
This independent model is why Gebhardt earned the AAA Insurance "Emerald Achievement Award" as the top new policy agency in Arizona in 2013, and why the Casa Grande Dispatch recognized us for "Best Customer Service." Most of our new clients come from referrals—neighbors telling neighbors that there's a better way to buy insurance.
Our agents drive the same roads you do. We understand that a hailstorm in Maricopa isn't the same as one in Flagstaff, and that your commute on I-10 carries different risks than surface streets in Florence. That local knowledge helps us recommend coverage that actually fits your life.
Want to see how much you could save? Get a free, no-obligation quote from Gebhardt Insurance Group. Call our Casa Grande office at (520) 836-3244, our Maricopa office at (520) 518-8008, or get a quote online.
Top 5 Ways to Save on Car Insurance in Arizona
1. Compare Quotes from Multiple Carriers
This is the single most effective way to lower your premium. According to the Insurance Information Institute, rates for identical coverage can vary by hundreds of dollars between companies—even in the same ZIP code.
Each carrier uses different algorithms to assess risk. One company might penalize you heavily for a minor speeding ticket while another barely considers it. One might offer steep discounts for your profession while another doesn't have that program.
The catch? Meaningful comparison shopping takes time. That's where an independent agent earns their keep. At Gebhardt, we can run your information through dozens of carriers in the time it would take you to fill out one online quote form. Learn more about how to compare car insurance rates effectively.
2. Bundle Your Auto and Home (or Renters) Insurance
Most carriers offer multi-policy discounts ranging from 5% to 25% when you combine auto insurance with homeowners, renters coverage, or mobile home insurance.
Beyond the discount, bundling simplifies your life:
One agency managing both policies
One renewal date to remember
Coordinated coverage that doesn't leave gaps
Easier claims process if an incident affects both your car and home
For mobile home and park model owners in Pinal County, bundling can be especially valuable. These properties have unique coverage needs, and carriers that specialize in both auto and mobile home insurance often offer the best combined rates.
3. Maintain a Clean Driving Record
Your driving history is the single biggest factor carriers use to set your rate. A clean record for three to five years can qualify you for "preferred driver" pricing that's substantially lower than standard rates.
Here's what hurts most:
At-fault accidents — Can increase premiums 30% to 50% for three to five years
DUI/DWI — Often doubles or triples your rate; may require SR-22 insurance
Speeding tickets — Moderate impact, but multiple violations compound quickly
Distracted driving citations — Increasingly penalized as distracted driving awareness grows
If you have a teen driver, check out our guide on safer driving tips for teenagers. Keeping them ticket-free protects your family's rates for years.
4. Adjust Your Deductibles Strategically
Your deductible—the amount you pay out of pocket before insurance kicks in—directly affects your premium. Raising your deductible from $500 to $1,000 typically reduces your premium by 15% to 30%.
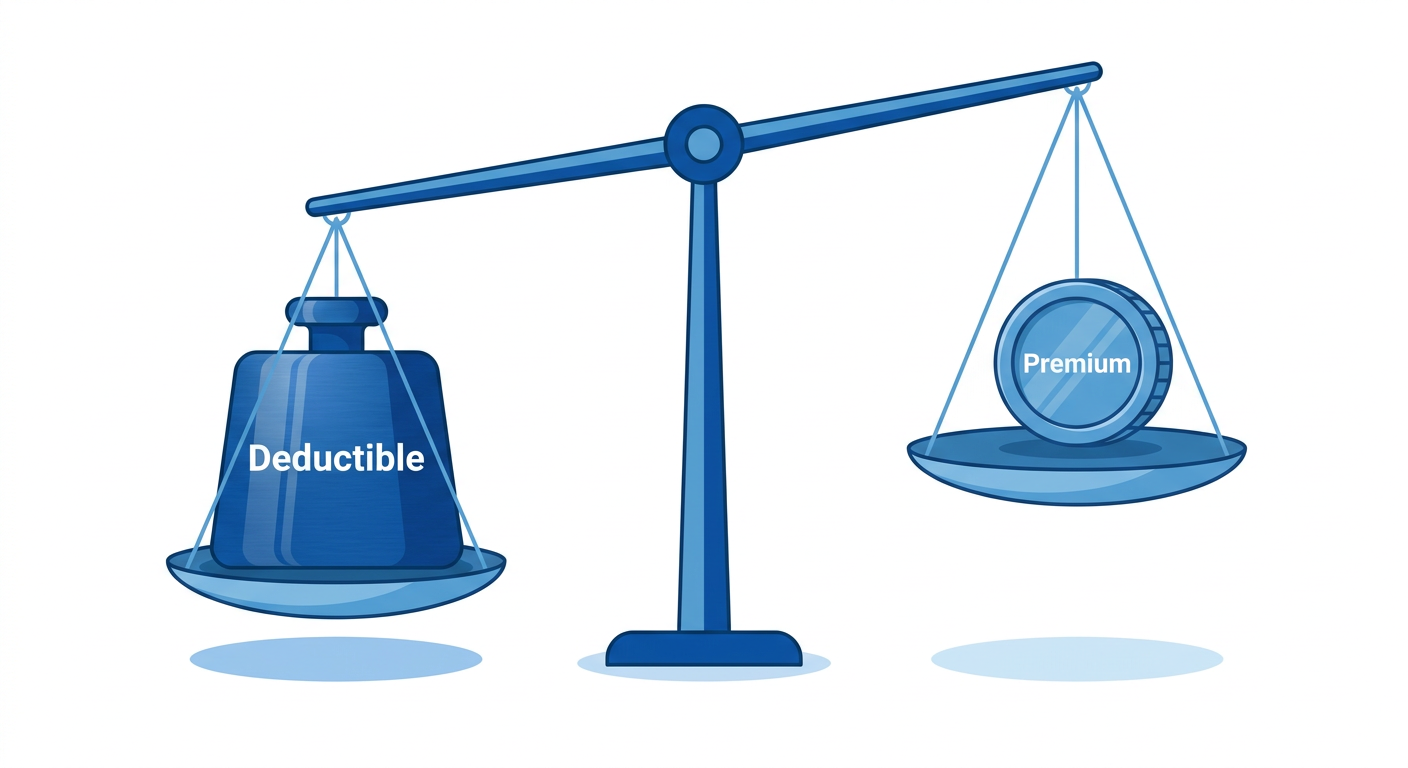
Adjusting your deductible is a balancing act between monthly savings and out-of-pocket risk.
This strategy makes sense if:
You have an emergency fund that could cover the higher deductible
You're a careful driver who rarely files claims
Your vehicle is older and you're carrying comprehensive coverage mainly for peace of mind
It doesn't make sense if a $1,000 unexpected expense would create financial hardship. The goal is savings, not stress.
For older vehicles, consider whether switching to liability-only coverage makes financial sense. If your car's market value is less than 10 times your annual comprehensive and collision premium, full coverage may not be worth the cost.
5. Ask About Every Available Discount
Carriers offer dozens of discounts, but they don't always advertise them. You have to ask. Common Arizona discounts include:
Safe driver programs — Telematics devices or apps that track your driving habits
Low mileage — If you drive less than 7,500 miles annually
Multi-vehicle — Insuring two or more cars on one policy
Professional/affinity groups — Teachers, first responders, military, AAA members, credit union members
Good student — For drivers under 25 with a B average or better
Defensive driving course — Completing an approved course can reduce rates for several years
Anti-theft devices — Factory or aftermarket alarms, GPS tracking, VIN etching
Paperless billing and autopay — Small but easy discounts for electronic payments
When you work with Gebhardt, we automatically check every discount you might qualify for across all 40+ carriers. Our car insurance discounts guide covers additional ways to lower your rate.
What Else Should Casa Grande and Maricopa Drivers Consider?
When Should I Review My Car Insurance?
At minimum, review your policy annually before renewal. But certain life changes warrant an immediate review:
Moving to a new address (even within Pinal County—ZIP codes matter)
Adding or removing a driver from your household
Buying or selling a vehicle
Major change in your commute or annual mileage
Paying off your car loan (lender requirements may change)
Turning 25 (rates often drop significantly)
Getting married (many carriers offer married discounts)
At Gebhardt, we conduct annual policy reviews proactively. If a better rate becomes available with another carrier, we let you know—even if it means moving your policy.
Is the Cheapest Car Insurance Always the Best Deal?
Not necessarily. A rock-bottom premium often comes with coverage gaps that cost you more after an accident. Watch for:
Minimum liability only — Arizona's $25,000/$50,000/$15,000 minimums may not cover a serious accident; you're personally liable for the difference
High deductibles — A $2,500 deductible lowers your premium but means $2,500 out of pocket for any claim
Excluded coverages — Some policies don't include uninsured motorist protection, which is critical when roughly 10% of Arizona drivers are uninsured
Claims service quality — A carrier that's difficult to work with during a claim costs you time, stress, and potentially money
The goal is the right coverage at the best price—not just the lowest number on a quote. Understanding common car insurance questions helps you make informed decisions.
How Does My Vehicle Affect My Arizona Car Insurance Rate?
Carriers consider several vehicle factors:
Vehicle age and value — Newer, more expensive cars cost more to insure
Safety ratings — Vehicles with high crash-test scores and advanced safety features often qualify for discounts
Theft rates — Some models are stolen more frequently, increasing comprehensive premiums
Repair costs — Luxury brands and vehicles with expensive parts cost more to repair after accidents
Engine size — High-performance vehicles typically carry higher premiums
Your vehicle identification number (VIN) tells insurers everything they need to know about your car's specifications, safety features, and history.
Conclusion
Saving on Arizona car insurance comes down to five proven strategies: comparing multiple carriers, bundling policies, maintaining a clean record, adjusting deductibles wisely, and claiming every discount you qualify for. The easiest way to execute all five is to let an independent agent do the work for you.
Gebhardt Insurance Group has been helping Casa Grande and Maricopa drivers find better rates since 2004. We shop more than 40 A-rated carriers so you don't have to make a dozen phone calls. There's no obligation, no pressure—just honest answers and competitive quotes.
Ready to see what you could save? Call our Casa Grande office at (520) 836-3244, our Maricopa office at (520) 518-8008, or request a free quote online. We're here when you're ready.
Frequently Asked Questions
How much is car insurance in Casa Grande, Arizona?
Car insurance in Casa Grande typically ranges from $1,200 to $2,400 annually for full coverage, depending on your driving record, vehicle, coverage levels, and the carrier. Rates vary significantly between companies, which is why comparing quotes through an independent agent like Gebhardt Insurance Group often uncovers savings.
Why should I use an independent insurance agent instead of going direct?
An independent agent shops multiple carriers with one application, comparing rates and coverage options you'd miss going direct. Gebhardt works with more than 40 A-rated companies, so we can find the best fit for your situation—and switch you to a better deal if rates change. There's no extra cost for this service.
Can I lower my car insurance if I have a speeding ticket in Arizona?
Yes, though options depend on the violation's severity and your overall record. Some carriers are more forgiving of minor infractions than others. Completing an Arizona defensive driving course may also reduce the ticket's impact. An independent agent can identify which carriers offer the best rates given your specific history.
Does bundling home and auto insurance really save money in Maricopa?
Bundling typically saves 5% to 25% on your combined premiums. Beyond the discount, you get simplified billing, coordinated coverage, and one agency handling both policies. For Maricopa homeowners and renters, bundling through Gebhardt means we can also shop both policies across multiple carriers for maximum savings.
How often should I shop for car insurance in Arizona?
Review your policy at least annually before renewal, or whenever you experience a major life change—moving, adding a driver, buying a vehicle, or paying off a car loan. At Gebhardt, we conduct proactive annual reviews and alert you if a better rate becomes available, even if it means switching carriers.
This article is for informational purposes only and does not constitute insurance advice or a binding quote. Coverage options, premiums, and policy terms vary by carrier, individual circumstances, and Arizona state regulations. Consult a licensed insurance professional for personalized recommendations. For current rates and coverage options, contact Gebhardt Insurance Group at (520) 836-3244 (Casa Grande) or (520) 518-8008 (Maricopa), or visit gebhardtinsurancegroup.com for a free quote.