Your delivery van slides on loose gravel near Coolidge and rear-ends a customer's truck. The damage? Substantial. The bigger problem? Your personal auto policy won't cover the accident because the vehicle was being used for business purposes. This scenario plays out across Pinal County more often than most business owners expect—and it's exactly why commercial auto insurance exists.
Personal auto policies often exclude coverage for accidents that occur during business activities.
Commercial auto insurance in Arizona protects vehicles used for business purposes—including liability for injuries and property damage, physical damage to your fleet, and coverage for employees driving company vehicles. Arizona requires minimum liability limits of $25,000/$50,000 for bodily injury and $15,000 for property damage, though most businesses need significantly higher limits to adequately protect their assets.
This guide covers what Arizona business owners in Casa Grande, Maricopa, and surrounding areas need to know about commercial auto coverage—from state requirements to cost factors to choosing the right policy for your operation. Whether you run a landscaping crew, manage a plumbing fleet, or coordinate deliveries across Pinal County, understanding these basics helps you make informed coverage decisions.
What Arizona Business Owners Need to Know About Commercial Auto Insurance
Commercial auto insurance covers vehicles owned, leased, or used by your business. This includes work trucks, vans, company cars, and specialized vehicles like dump trucks or refrigerated delivery vehicles. The coverage kicks in when vehicles are used for business activities—something personal auto policies explicitly exclude.
Arizona law requires all registered vehicles to carry minimum liability coverage. For commercial vehicles, this means at least $25,000 per person and $50,000 per accident for bodily injury, plus $15,000 for property damage. However, these minimums rarely provide adequate protection for business owners. A single serious accident can easily exceed these limits, leaving your business responsible for the difference.
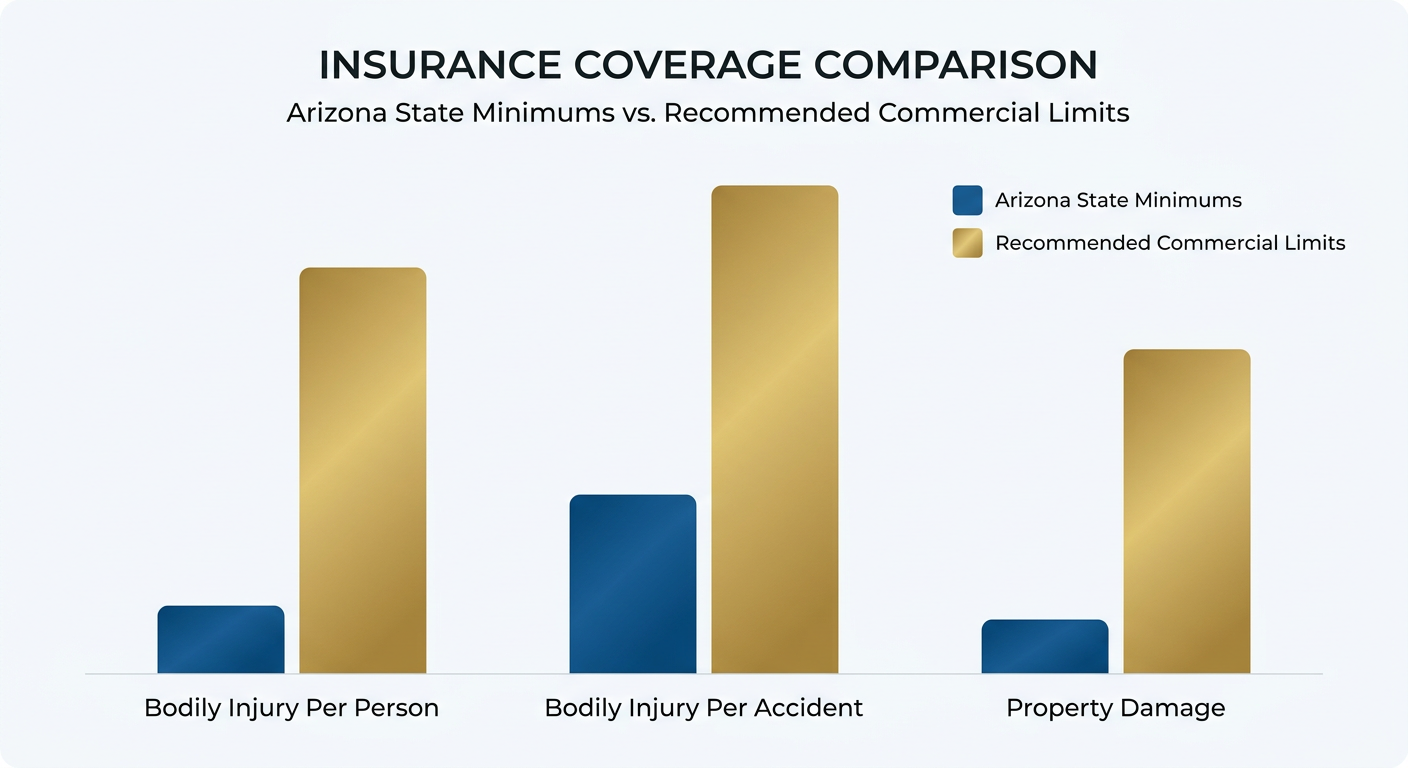
Arizona's state minimums often fall short of the actual costs of a serious business accident.
Commercial auto policies typically include several coverage components:
Liability coverage pays for injuries and property damage you cause to others
Collision coverage repairs or replaces your vehicle after an accident
Comprehensive coverage protects against theft, vandalism, weather damage, and hitting animals—common along the I-10 corridor
Medical payments coverage pays for medical expenses regardless of fault
Uninsured/underinsured motorist coverage protects you when other drivers lack adequate insurance
Arizona's desert environment creates specific risks that affect commercial fleets. Monsoon season floods can damage vehicles in low-lying areas around Casa Grande and Florence. Extreme summer heat accelerates tire blowouts and mechanical failures. Dust storms along I-10 contribute to multi-vehicle accidents. These regional factors influence both coverage needs and premium calculations.
Regional risks like monsoons and dust storms require specific coverage considerations.
Many business owners mistakenly believe their personal auto policy covers occasional business use. It doesn't. If you're transporting goods, equipment, or materials for business purposes—or if employees drive your vehicles—you need commercial coverage. Using a personal policy for business activities can result in denied claims when you need protection most.
How Gebhardt Insurance Group Helps Arizona Business Owners
Finding the right commercial auto policy requires comparing options across multiple insurance carriers—each with different appetites for various business types, fleet sizes, and driver profiles. As an independent insurance agency serving Casa Grande and Maricopa since 2004, Gebhardt Insurance Group shops more than 40 A-rated carriers to find competitive rates for local business owners.
The independent agent difference matters for commercial coverage. Captive agents—those who work for a single carrier like State Farm or Allstate—can only offer their company's products. If their carrier doesn't write favorable rates for your business type or has restrictions on certain vehicle classes, you're out of luck. Gebhardt's team compares options from Progressive Commercial, AAA, and dozens of other carriers to match your specific operation.
Our agents understand Pinal County business operations. Steve, Crystal, Maria, Sarah, and Andrea work with contractors, landscapers, delivery services, and agricultural operations across the region. They know which carriers offer favorable rates for construction fleets, which ones specialize in delivery vehicles, and which provide the best coverage for specialized equipment. This local expertise translates to better coverage recommendations.
Gebhardt earned the AAA Insurance "Emerald Achievement Award" as the top new policy agency in Arizona and "Best Customer Service" recognition from the Casa Grande Dispatch. Most new clients come from referrals—business owners recommending our team to other business owners. That reputation matters when you're trusting someone with your fleet protection.
When claims happen, your Gebhardt agent advocates on your behalf. Because we place business with multiple carriers, we have leverage and relationships that help move claims forward. We're not just policy sellers—we're partners in protecting your business assets.
Ready to compare commercial auto rates for your Arizona business? Get a free, no-obligation quote from Gebhardt Insurance Group. Call our Casa Grande office at (520) 836-3244, our Maricopa office at (520) 518-8008, or request a quote online.
Factors That Affect Your Commercial Auto Insurance Costs
Commercial auto premiums vary significantly based on your business profile, vehicle types, and driver history. Understanding these factors helps you make informed decisions about coverage and identify opportunities to reduce costs.
Vehicle type and use heavily influence rates. A landscaping truck used within Casa Grande costs less to insure than a long-haul delivery van covering the Phoenix-Tucson corridor daily. Specialized vehicles like dump trucks, refrigerated units, or vehicles carrying hazardous materials typically carry higher premiums due to increased risk exposure.
Driver records affect every commercial policy. Carriers review driving histories for all employees who operate company vehicles. Accidents, DUIs, and moving violations increase premiums—sometimes substantially. Implementing driver safety programs and responsible driving training can help control costs over time.
Fleet size creates both challenges and opportunities. Larger fleets mean more exposure, but they also qualify for volume discounts with many carriers. Some insurers specialize in small fleets of three to five vehicles, while others prefer larger operations with fifteen or more units.
Money-saving strategies that actually work:
Bundle commercial auto with your commercial property coverage or general liability policy
Choose higher deductibles if your business can absorb smaller losses
Install GPS tracking and telematics—some carriers offer discounts for fleet monitoring
Maintain clean driver records and implement written safety policies
Review coverage annually—as your fleet changes, your policy should adapt
Arizona's competitive insurance market means rates vary widely between carriers. The contractor paying a certain rate through one carrier might qualify for significantly different rates through another. This is where working with an independent agent pays off—we identify which carriers offer the best fit for your specific business profile.
Do I need commercial auto insurance if employees drive their own cars for work?
Yes, you likely need hired and non-owned auto coverage—a policy addition that protects your business when employees use personal vehicles for work tasks. If an employee causes an accident while running a work errand, the injured party can sue your business, not just the employee. This coverage fills that gap and typically costs less than insuring dedicated fleet vehicles.
This situation is common among Casa Grande and Maricopa service businesses where employees drive personal vehicles to job sites or client meetings. Your business insurance portfolio should address this exposure.
What's the difference between commercial auto and personal auto insurance?
Commercial auto policies are designed for business use and offer higher liability limits, coverage for multiple drivers, and protection for business-owned vehicles and equipment inside them. Personal auto policies specifically exclude business use—meaning claims for accidents during business activities will likely be denied. The coverage structures, premium calculations, and policy terms differ substantially between the two.
If you're unsure whether your current coverage is adequate, the Gebhardt team can review your situation and identify any gaps.
How do I add a new vehicle to my commercial auto policy?
Contact your insurance agent immediately when you acquire a new business vehicle. Most commercial policies provide automatic coverage for newly acquired vehicles for a limited period—typically 30 days—giving you time to formally add the vehicle. Your agent will need the vehicle identification number (VIN), purchase price, and intended use to update your policy. Adding vehicles promptly ensures no coverage gaps exist if an accident occurs.
Conclusion: Protect Your Business Fleet the Right Way
Commercial auto insurance isn't optional for Arizona businesses using vehicles—it's essential protection against liability exposure that could threaten your entire operation. Understanding your coverage needs, Arizona's requirements, and the factors affecting your rates positions you to make smart decisions about protecting your fleet.
Rather than calling multiple carriers yourself, let Gebhardt Insurance Group do the shopping for you. Our team compares rates from over 40 carriers to find coverage that fits your business operations and budget. Call Casa Grande at (520) 836-3244 or Maricopa at (520) 518-8008, or get a free quote online—no pressure, just straightforward answers about protecting your business.