Living in a mobile home or manufactured home in Arizona comes with unique insurance challenges. Desert heat warps siding, monsoon winds test tie-downs, and many park model communities have specific coverage requirements your standard homeowners policy won't meet.
Mobile home insurance in Arizona typically costs between $300 and $1,500 per year, depending on your home's age, location, construction type, and chosen coverage limits. Residents in Casa Grande, Maricopa, and Pinal County often find better rates by working with an independent agent who can compare multiple carriers rather than accepting the first quote from a single insurer.
At Gebhardt Insurance Group, we specialize in helping Arizona mobile home owners find the right coverage at the right price. This guide breaks down what affects your premium, what coverage you actually need, and how to save money without sacrificing protection.
What You Need to Know About Mobile Home Insurance in Arizona
Mobile home insurance—sometimes called manufactured home insurance—works differently than standard homeowners coverage. Arizona doesn't legally require you to carry mobile home insurance, but your lender will if you have a loan, and most mobile home parks require proof of coverage before you can move in.
Dwelling coverage protects the physical structure of your mobile home, including attached features like decks, porches, and carports. Personal property coverage pays to replace your belongings if they're damaged or stolen. Liability coverage protects you if someone gets injured on your property and sues.
Arizona's desert climate creates specific risks that affect both your coverage needs and your premium. The Arizona Department of Insurance and Financial Institutions receives thousands of complaints each year related to weather damage claims—many involving mobile homes unprepared for monsoon season.
Monsoon winds regularly exceed 60 mph in Pinal County, putting stress on mobile home roofs, skirting, and anchoring systems. Extreme summer heat—routinely above 110°F in Casa Grande and Maricopa—causes expansion and contraction damage to seals, roofing materials, and HVAC systems that standard policies may not fully cover.
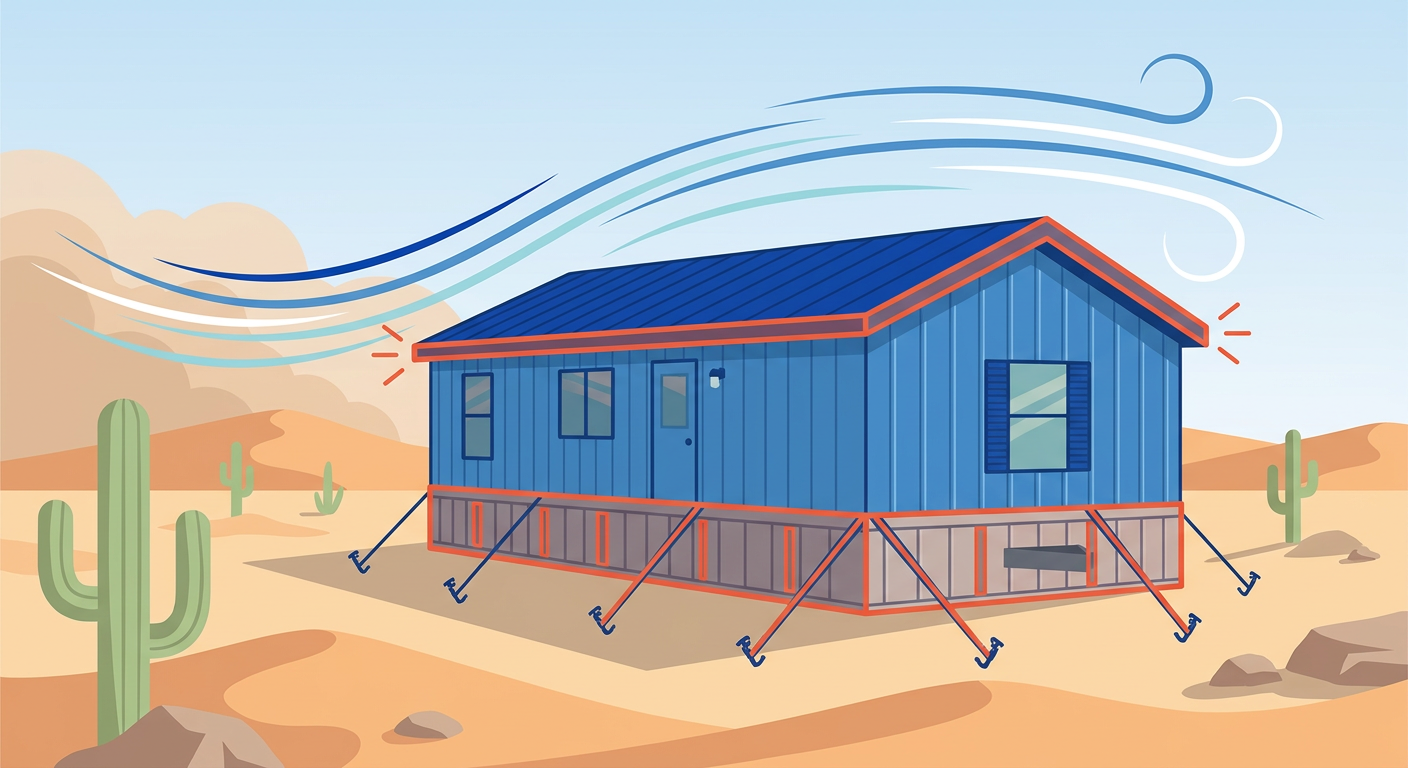
High-velocity winds impact specific structural points like skirting and tie-downs that standard policies may overlook.
Common Coverage Gaps Arizona Mobile Home Owners Miss
Flood damage: Standard mobile home policies exclude flood damage entirely. If you're near a wash or flood zone—common throughout Pinal County—you need separate flood coverage.
Earthquake coverage: Arizona does experience seismic activity. This is typically an add-on, not included automatically.
Trip collision: If you ever relocate your mobile home, you need specific coverage for damage during transport.
Replacement cost vs. actual cash value: Actual cash value policies depreciate your home's worth, meaning you'll receive far less than it costs to replace an older mobile home.
Understanding how mobile and modular home classification works helps you avoid buying the wrong policy type—a mistake that can delay or deny claims.
How Gebhardt Insurance Group Helps Arizona Mobile Home Owners
When you call Progressive, AAA, or Foremost directly, you get one quote from one carrier. When you call Gebhardt Insurance Group, we shop more than 40 A-rated insurance carriers on your behalf and present you with multiple options.
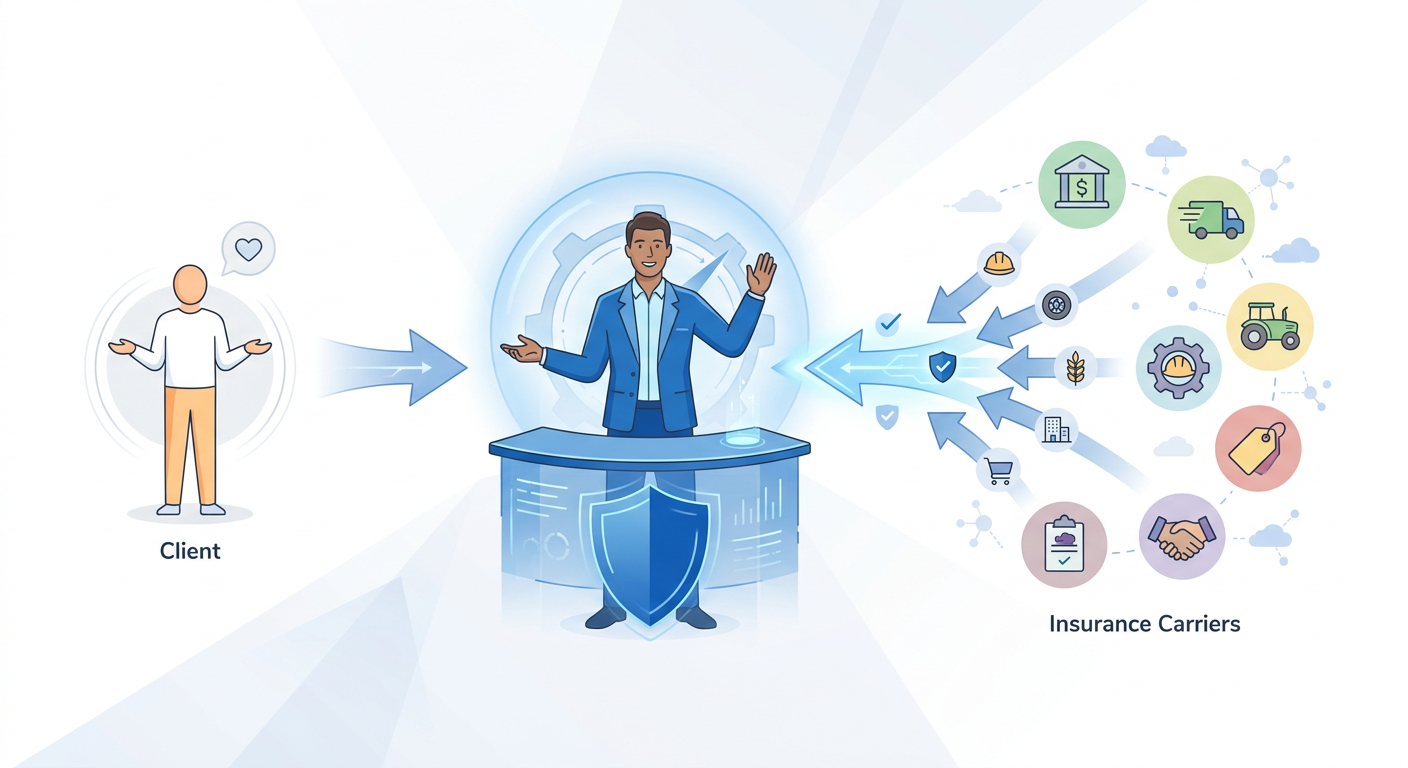
We act as a single point of contact to access dozens of competing quotes.
This independent agent model means we work for you—not for any single insurance company. We have no incentive to push you toward a specific carrier. Our job is finding the policy that fits your mobile home, your budget, and your risk tolerance.
Our team—Steve, Crystal, Maria, Sarah, and Andrea—lives and works in Casa Grande and Maricopa. We understand that mobile home communities like Palm Creek in Casa Grande or Rancho El Dorado in Maricopa have different insurance requirements. We've helped hundreds of residents navigate park requirements, lender demands, and the confusion of comparing coverage options.
Gebhardt Insurance Group earned the AAA Insurance "Emerald Achievement Award" as Arizona's top new policy agency in 2013, and the Casa Grande Dispatch recognized us for "Best Customer Service." Most of our new clients come from referrals—neighbors recommending us to neighbors.
We also conduct annual policy reviews at no charge. Insurance rates change, your home's value changes, and better options become available. We proactively check whether you can get the same coverage for less money or better coverage for the same premium.
Ready to see what you could save? Get a free, no-obligation quote from Gebhardt Insurance Group. Call our Casa Grande office at (520) 836-3244, our Maricopa office at (520) 518-8008, or get a quote online.
What Factors Affect Mobile Home Insurance Costs in Arizona?
Your premium isn't random. Insurance carriers use specific factors to calculate your rate, and understanding these gives you leverage to reduce costs.
Age and Condition of Your Mobile Home
Older mobile homes cost more to insure. Homes built before 1976—before HUD manufacturing standards took effect—are considered higher risk and may be difficult to insure at all. Homes built after 1976 with HUD certification tags typically qualify for better rates.
Carriers also consider your home's current condition. Updated electrical systems, newer roofing, and storm-resistant features like hurricane straps can lower your premium. Following proper mobile home maintenance practices not only protects your home but can qualify you for discounts.
Location Within Arizona
Where your mobile home sits matters. Homes in established parks with security features, fire hydrants, and paved roads typically cost less to insure than homes on rural private land. Proximity to fire stations affects rates—a home within five miles of a fire department pays less than one 15 miles away.
Flood zone designations also impact cost. FEMA flood maps show whether your location is in a high-risk zone, which would require separate flood insurance.
Coverage Limits and Deductibles
Higher coverage limits mean higher premiums. But choosing limits too low can leave you underinsured when you need to file a claim. The Insurance Information Institute recommends insuring your home for its full replacement cost—what it would actually cost to replace, not its current market value.
Raising your deductible—the amount you pay out of pocket before insurance kicks in—lowers your premium. A $1,000 deductible will cost less monthly than a $500 deductible, but you need to have that cash available if you file a claim.
Your Claims History and Credit
Previous claims on any insurance policy can raise your rates. Arizona allows insurers to use credit-based insurance scores, so maintaining good credit can help keep premiums lower.
Practical Tips to Lower Your Mobile Home Insurance Premium
You don't have to accept the first quote you receive. These strategies can meaningfully reduce what you pay without reducing your protection.
Bundle Your Policies
Carrying your mobile home insurance and auto insurance with the same carrier typically saves 10-25% on both policies. If you also have an RV, boat, or motorcycle, bundling those adds more savings. Ask your agent about multi-policy discounts—this is one of the fastest ways to reduce your total insurance spend.
Install Safety and Security Features
Smoke detectors, deadbolt locks, fire extinguishers, and security systems can qualify you for discounts. Some carriers offer specific discounts for:
Monitored alarm systems
Smoke and carbon monoxide detectors
Hurricane straps or tie-downs
Impact-resistant roofing
Updated electrical and plumbing systems
Ask About Available Discounts
Carriers offer discounts that agents don't always mention unless you ask. Common mobile home insurance discounts include:
Claims-free discount: No claims in 3-5 years
New home discount: Homes less than 10-15 years old
55+ community discount: Age-restricted communities often qualify
Paid-in-full discount: Paying annually instead of monthly
Loyalty discount: Staying with the same carrier for multiple years
Learning about available insurance discounts for all your policies helps you maximize savings across your entire insurance portfolio.
Review Your Policy Annually
Rates change. Carriers enter and exit markets. Your home's value and your coverage needs evolve. An annual review with your agent ensures you're not overpaying or underinsured.
This is where working with an independent agency like Gebhardt pays off. If your current carrier raises rates, we can shop your policy to 40+ other carriers without you making a single additional phone call.
How Much Does Mobile Home Insurance Cost in Casa Grande?
Mobile home insurance in Casa Grande typically ranges from $350 to $1,200 annually, depending on your home's age, value, and the coverage limits you select. Homes in established 55+ communities like Sunland Springs or Palo Verde often qualify for lower rates than standalone mobile homes on private lots.
The Casa Grande area's proximity to fire services and lower crime rates compared to larger metro areas can work in your favor. However, monsoon flood risk in certain zones may require additional coverage. Contact Gebhardt's Casa Grande office for a specific quote based on your home and location.
Why Are Mobile Home Insurance Rates Different in Maricopa vs. Phoenix?
Maricopa residents often pay less for mobile home insurance than Phoenix metro residents. Several factors contribute to this difference. Maricopa has lower population density, which correlates with lower theft and vandalism rates. The city's newer infrastructure means better fire response times for many neighborhoods.
However, Maricopa's location means different wind and dust exposure than central Phoenix. Your specific address, distance from emergency services, and whether you're in a park or on private land all influence your final rate. An independent Maricopa insurance agency can show you how rates compare across carriers for your exact situation.
Do I Need Mobile Home Insurance If I Own My Home Outright?
Arizona doesn't legally require mobile home insurance if you own your home free and clear with no lender. However, going without insurance means you personally absorb the full cost of any damage, theft, or liability claim.
Consider what it would cost to replace your mobile home out of pocket if a monsoon wind damaged the roof, or if a fire destroyed your belongings. If a visitor slipped on your steps and sued you, could you pay a legal judgment without liability coverage?
For most Arizona mobile home owners, even without a lender requirement, the cost of insurance is far less than the financial risk of going without it. You can read more about factors that determine insurance costs to understand how coverage protects your financial stability.
Conclusion: Get Your Free Mobile Home Insurance Quote
Mobile home insurance in Arizona doesn't have to be expensive or confusing. Understanding what affects your premium—age, location, coverage limits, and available discounts—puts you in control. Working with an independent agent who shops multiple carriers ensures you're not overpaying for the protection you need.
Let Gebhardt Insurance Group do the shopping for you. We've helped Casa Grande, Maricopa, and Pinal County mobile home owners find affordable coverage since 2004. Call our Casa Grande office at (520) 836-3244, our Maricopa office at (520) 518-8008, or request your free quote online. No pressure, no obligation—just honest answers and real options.
Frequently Asked Questions
How much does mobile home insurance cost in Arizona?
Mobile home insurance in Arizona typically costs between $300 and $1,500 per year. Your exact premium depends on your home's age, construction type, location, coverage limits, and deductible. Homes built after 1976 with HUD certification generally qualify for lower rates than older manufactured homes.
Is mobile home insurance required in Arizona?
Arizona state law does not require mobile home insurance. However, if you have a loan on your home, your lender will require coverage. Most mobile home parks also require proof of insurance before allowing residents to occupy a space. Even without requirements, coverage protects you from significant financial loss.
What does mobile home insurance cover?
Standard mobile home insurance covers your dwelling structure, personal belongings, and liability if someone is injured on your property. Most policies also include additional living expenses if you're displaced during repairs. Flood and earthquake damage typically require separate coverage or policy add-ons.
How many insurance companies does Gebhardt compare for mobile home quotes?
Gebhardt Insurance Group shops more than 40 A-rated insurance carriers to find mobile home coverage options. As an independent agency, we're not limited to one company's products. This means we can compare rates and coverage from multiple insurers to find the best fit for your specific situation and budget.
Can I get mobile home insurance if my home was built before 1976?
Pre-1976 mobile homes can be more difficult to insure because they were manufactured before HUD safety standards took effect. Some carriers won't cover them at all. Gebhardt Insurance Group works with specialty carriers that do insure older mobile homes, though premiums are typically higher and coverage options may be more limited.